IMF Reviews Urge Realism, While Analyst Warns of Three Shocks Lifting Rates
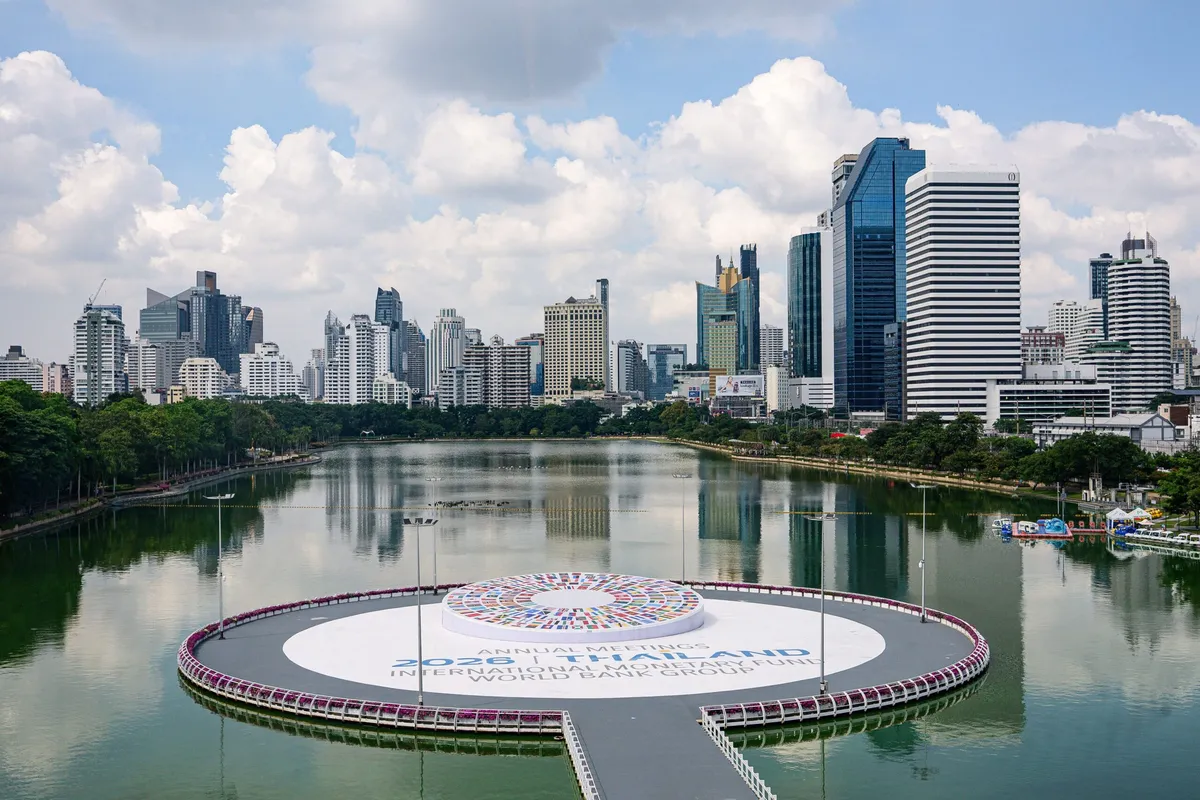
Finance ministers and central bank governors have gathered in Bangkok for the IMF-World Bank Annual Meetings, where Atlantic Council experts are tracking four new IMF policy reviews and warning that an energy shock, AI borrowing and rising public debt are pushing up long-term interest rates.
- Four IMF reviews cover low-income debt sustainability, conditionality, the FSAP and surveillance.
- Martin Mühleisen proposes an annual implementation scorecard to hold IMF management accountable.
- Hung Tran cites a ten-year US Treasury yield of 5.31 percent as of October 5, the highest levels since 2002.
- Tran names energy, AI demand and public debt shocks as drivers of higher long-term rates.
- Georgieva said high rates are likely to remain over the long term.
Four IMF reviews call for more realism and selectivity
According to Martin Mühleisen, a nonresident senior fellow at the Atlantic Council's GeoEconomics Center and a former IMF chief of staff and strategy director, four major reviews published in recent days give a candid account of the fund's core work. They cover debt sustainability in low-income countries, program design and conditionality, the financial sector assessment program (FSAP), and economic surveillance. Together, he writes, they call for more realistic analysis, greater selectivity, better integration across policy areas and stronger follow-through.
On debt, the framework for low-income countries has focused on external debt in foreign currency. Domestic borrowing in local currency has grown in importance, opening new avenues for shocks. The review proposes new indicators for gross financing needs and interest payments, a domestic-debt module and a stress test for domestic financing. Mühleisen says an incomplete diagnosis can delay debt restructuring and encourage more lending into an unsustainable situation.
The conditionality review asks for more credible macroeconomic assumptions, stronger contingency planning and better sequencing of structural reforms. It suggests programs develop a medium-term reform strategy built around measures critical to success. Mühleisen reads this as an implicit acknowledgment that programs can become overloaded.
The surveillance review seeks sharper prioritization of country work and more contingent policy advice, while also asking staff to deepen work on external spillovers, AI, structural policies and emerging risks. The FSAP review proposes more modular, risk-based assessments, closer links to Article IV consultations and more actionable recommendations, as the program now reaches beyond banks to nonbank institutions, digital finance, cyber threats, climate risks and cross-border interconnections.
Skepticism about follow-through
Mühleisen calls the recommendations sound but familiar from earlier reviews, which gives grounds for doubt about whether IMF management and the Executive Board will heed them. He notes that how the IMF communicates its advice was not part of the surveillance review, which he calls an important shortcoming.
His proposal is that the IMF publish an annual implementation scorecard and explain major departures from the new guidance. This, he argues, would keep the discretion needed for country work while making outcomes more transparent. Without visible accountability, he warns, the next review cycle five years from now is likely to return to the same questions.
Three shocks and rising long-term rates
Hung Tran, a nonresident senior fellow at the GeoEconomics Center and former IMF deputy director, describes three concurrent shocks: an energy supply shock, an AI demand shock and a public sector debt shock. He says conflict in the Middle East has disrupted oil and gas supply and raised crude prices to more than one hundred dollars a barrel, forcing major central banks to tighten. Ten-year US Treasury yields have reached their highest levels since 2002.
On AI, Tran cites a Goldman Sachs estimate that global AI investment expenditure would exceed one trillion dollars in 2026, or 0.9 percent of global GDP, rising to 1.3 percent in 2027 and 1.4 percent in 2028. Public debt of advanced economies has reached a new high of $102 trillion, or 91 percent of global GDP, driven by fiscal deficits of 5-6 percent of global GDP.
Tran maps the shocks onto the components of the ten-year nominal Treasury yield, at 5.31 percent as of October 5. The equilibrium real rate r*, lifted by AI funding needs, is estimated at 2.95 percent, and the inflation premium, driven by the energy shock, at 2.36 percent. The term premium is estimated at 1.08 percent.
Equity valuation and concentration risk
Tran notes that IMF Managing Director Kristalina Georgieva said in her curtain-raiser speech that high rates are likely to remain over the long term, with negative implications for growth and equity valuation. He puts the S&P 500 price-to-earnings ratio at around 26.6, against a long-term average of 16.2, and says the ten-year Shiller CAPE ratio has exceeded 41.
He also points to concentration: ten top companies approach 40 percent of the S&P 500, and AI and high-tech capital expenditure, at 1.8-2.5 percent of US GDP, has contributed about half of US GDP growth in recent quarters. Persistently high rates, he concludes, threaten overvalued US equity markets, and policymakers can help by putting their fiscal houses in order.